Agent-Based Modeling (ABM) in Finance
We look at Agent-Based Modeling in finance. Identifies individual buyers and sellers, how big they are, and what they're motivated to do.
We look at Agent-Based Modeling in finance. Identifies individual buyers and sellers, how big they are, and what they're motivated to do.
Inflation-Linked Bonds vs. Nominal Bonds - We look at them from various angles, including allocation approaches between them in a portfolio.
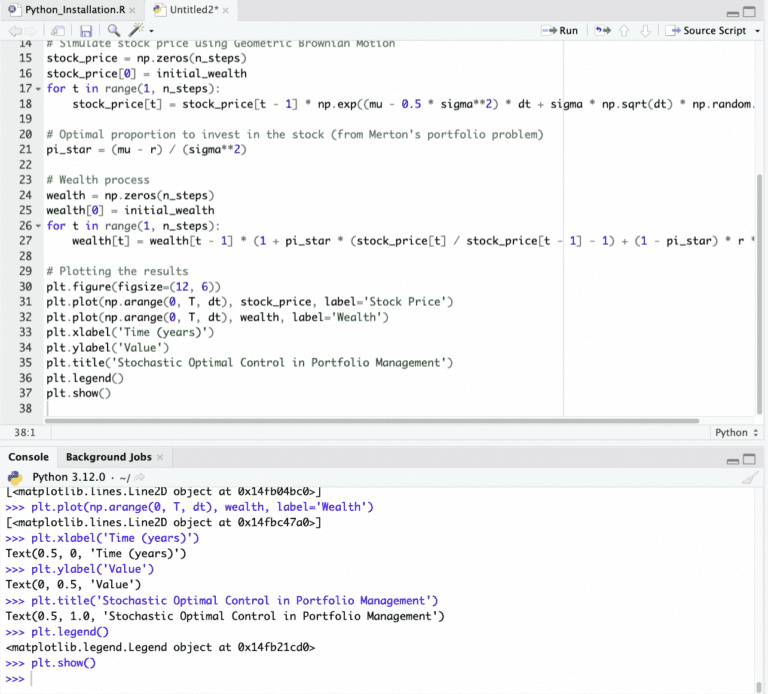
Stochastic Optimal Control - we look at how this approach is used in financial decision-making. We also include a coding example problem.
Python vs. C++ - We look at the applications and pros and cons of each for financial algorithm development. Plus, example algorithms in each.
The financial markets and the economy are inextricably linked together. Learn about the importance of market equilibriums.
We look at the best Python libraries for various forms of trading, financial, and portfolio tasks. We look beyond Pandas and NumPy.
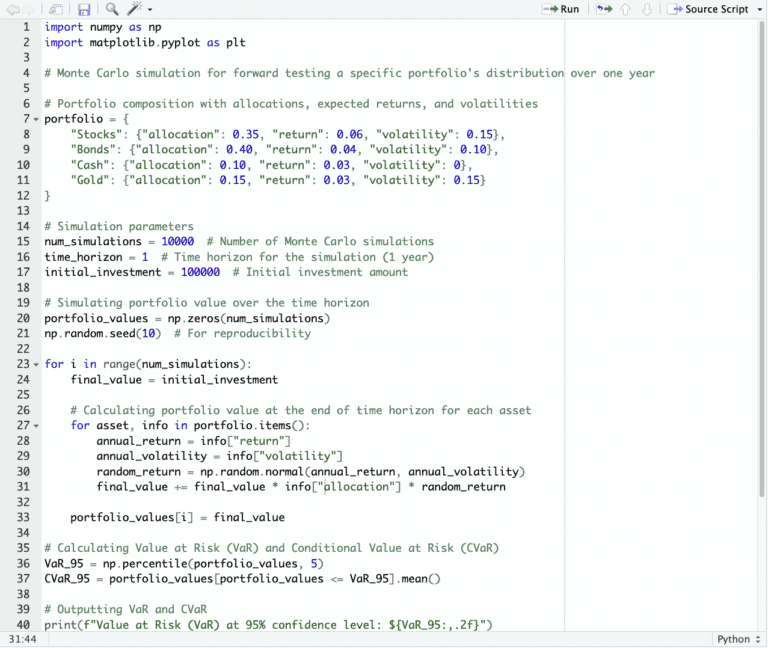
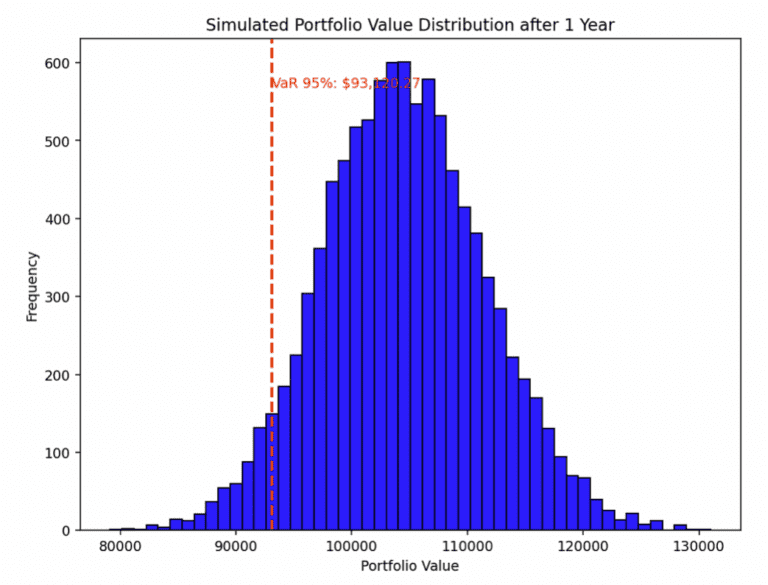
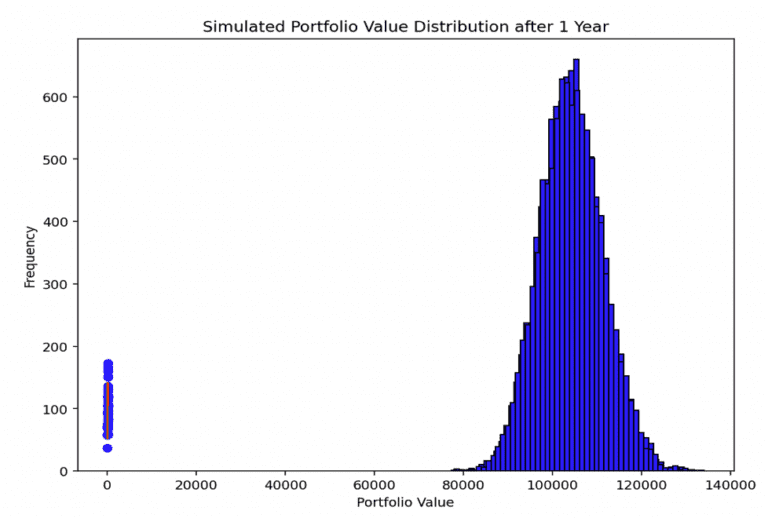
Monte Carlo Simulation in Python - We run examples involving portfolio simulations and risk modeling. List of all applications.
We look at Estimation Theory in finance and how it's used in quantitative models in finance. Also included are Python examples.
Gold vs. Silver - We look at monetary demand influence, industrial use, diversification, rarity, price ratio, and pricing considerations.
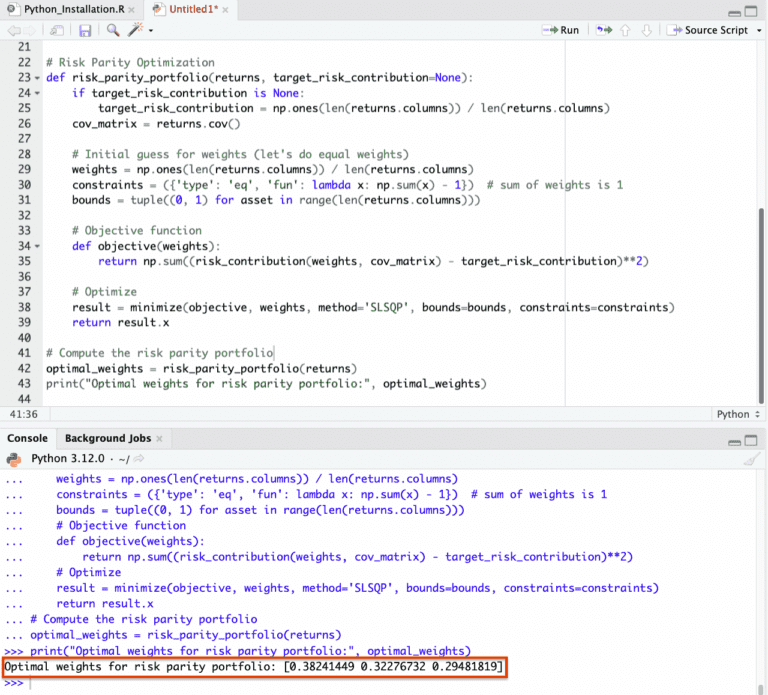
We look at the applications of Group Theory, a form of abstract algebra, in finance. We'll also do an example of a risk parity portfolio.