Maximum Downside Exposure (MDE)
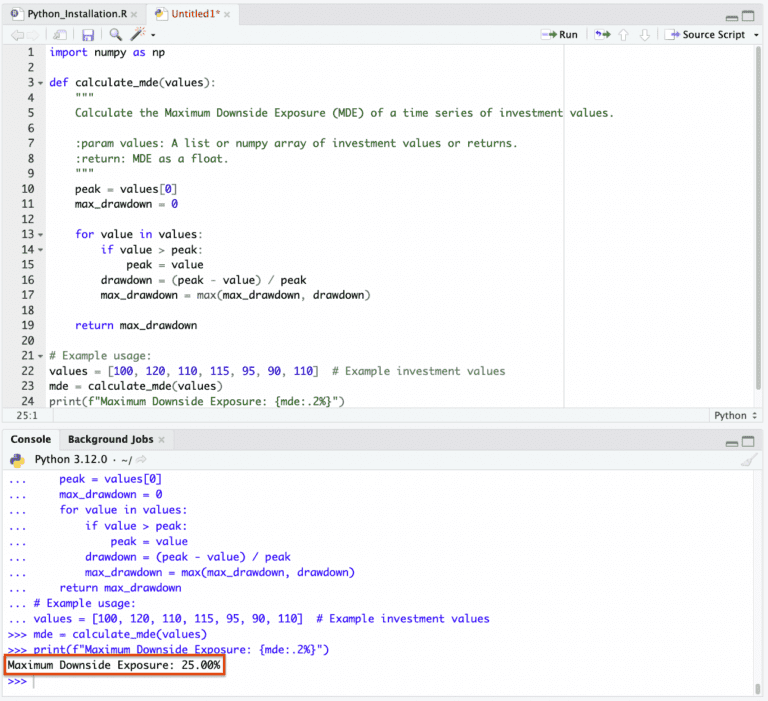
Maximum Downside Exposure (MDE) is a risk metric that can help us understand and model worst-case scenarios for investment portfolios.
Maximum Downside Exposure (MDE) is a risk metric that can help us understand and model worst-case scenarios for investment portfolios.
We look at Modigliani Risk-Adjusted Performance as another way to assess risk-adjusted performance in your portfolio.
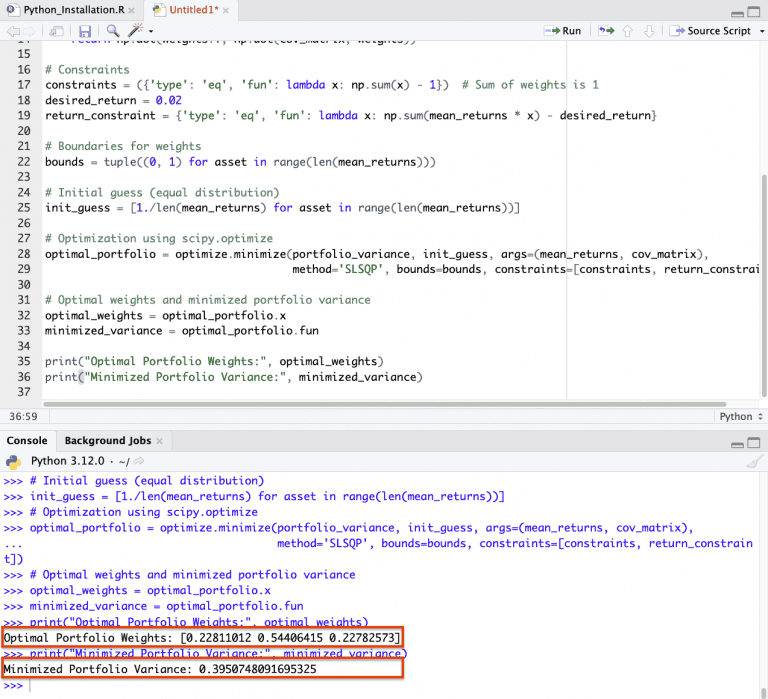
We look at conic solvers in financial optimization. We look at its applications, math, and provide an example optimization problem in Python.
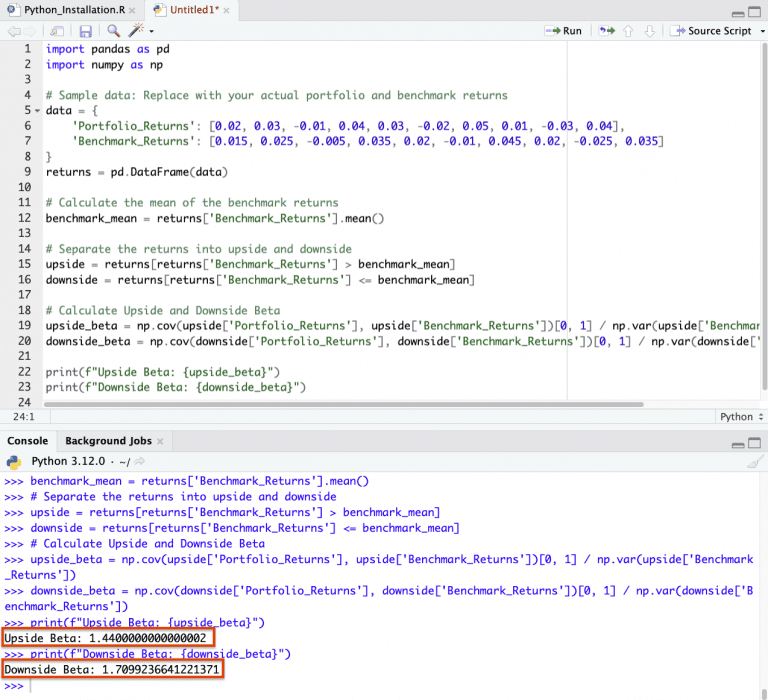
Dual-Beta divides market risk into Downside Beta and Upside Beta, assessing how a stock or asset behaves in market downturns & upturns.
Upside Potential Ratio. Learn how to use it to evaluate investment performance, and why upside potential ratio is so important for traders.
We look at the Bias Ratio - what it is, how its calculated, significance, application, pros and cons, and more.
What Is Multicollinearity? Why is it important for traders and investors to understand multicollinearity in regression models?
We show How to Install Python in R Studio. Use our scripts for easy setup. We also provide a sample Python Script for you to test.
We look at Style Drift. What it is, causes, impact, and how to monitor and manage style drift. Learn more about style drift here.
What is the Lipper Average (Lipper Index) and why and how is it used? What are its drawbacks? We look at these questions and more.