Derivatives Pricing – Terms, Definitions & Topical Outline
Derivative pricing involves models like Brownian motion and risk-neutral valuation to predict price movements and valuations.
Derivative pricing involves models like Brownian motion and risk-neutral valuation to predict price movements and valuations.
We look at key financial math tools, including Stochastic Calculus, Risk Models, Optimization & PDEs.
Theoretical finance forms the backbone of our understanding of how markets operate. Let´s look at some foundational concepts.
Study plan for those aspiring to become financial programmers, financial engineers, and/or algorithmic traders. Undergraduate, master's and PhD level.
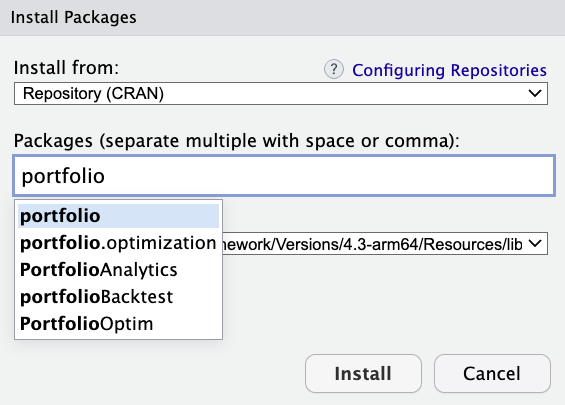
What are the top programming languages for portfolio optimization? What are their libraries and packages? We've got all that covered.
We look through the best BA/BS, MA/MS, MBA, and PhD programs in quantitative finance, with around 20 schools for each level.
We look at Exter's Pyramid – a guide ranking asset liquidity & risk, essential for establishing preferences during financial turbulence.
Mathematical Modeling for American Options vs. European Options. Learn how modelling differs between these two option types.
We look at the Feynman-Kac formula in bridging stochastic processes and partial differential equations (PDEs). How can it be used in finance?
We explore Q World's risk-neutral valuation for derivatives and P World's real-probability approach for trading and investment decisions.